Need to Know: Health Plans & Medical IRAs

Need to Know: Health Plans & Medical IRAs
We are available for personal consultation. No cost, no obligation. Just contact us.

Wednesday, January 22, 2014

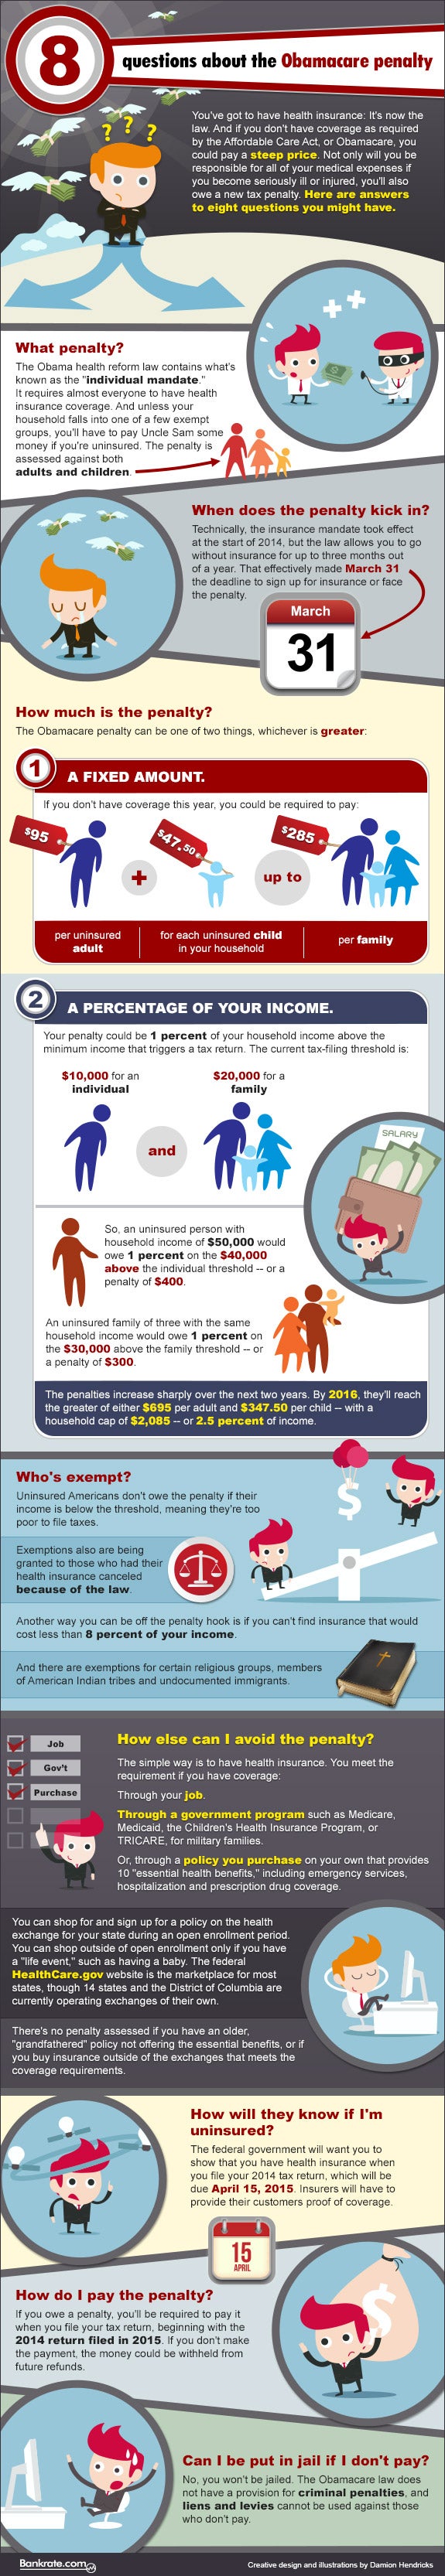
8 Questions about the Obamacare Penalty

What is the penalty?
When does the penalty kick in?
How much is the penalty?
Who's exempt?
How else can I avoid the penalty?
How will they know if I'm uninsured?
How do I pay the penalty?
Can I be put in jail if I don't pay?
               No. They can only collect the penalty by reducing your future tax refunds.


Saturday, January 18, 2014

WWII -vs- Obamacare website


Worth noting:


During the 3½ years of World War II that started with the Japanese bombing of Pearl Harbor in December 1941 and ended with the surrender of Germany and Japan in 1945, the US produced...
  • 22 aircraft carriers
  • 8 battleships
  • 48 cruisers
  • 349 destroyers
  • 420 destroyer escorts
  • 203 submarines
  • 34 million tons of merchant ships
  • 100,000 fighter aircraft
  • 98,000 bombers
  • 24,000 transport aircraft
  • 58,000 training aircraft
  • 93,000 tanks
  • 257,000 artillery pieces
  • 105,000 mortars
  • 3,000,000 machine guns
  • 2,500,000 military trucks
We put 16.1 million men in uniform in the various armed services, invaded Africa, invaded Sicily and Italy, won the battle for the Atlantic, planned and executed D-Day, marched across the Pacifric and Europe, developed the atomic bomb and ultimately conquered Japan and Germany.

It's worth noting that during the almost exact amount of time, the Obama administration couldn't build a functioning website.


Thursday, January 9, 2014

ACA Winners & Losers


In Ponzi schemes there are Winners and Losers. Winners are the ones who get more than their money back. ACA is not a Ponzi scheme. It’s more like a shell game.  If you find the pea under the little cup, you’re a Winner. But just try to keep your eye on it as they move those little cups around.

ACA Winners & Losers

Winners: People with lots of kids (especially college age and unpaid service work)*
               Self-employed, 1099 independent contractors and others who control their own wage AND
               The business pays for a lot of their goodies (vehicles, gas, cellphone, electronics, etc.)
               Millionaires (millions in assets combined with modest AGI income)

Losers:  Single people
               Married, dual income
               W-2 employees  
                *Family Size of 5 or more gets subsidy even with a six-figure + income.                          

As I sit down with self-employed people with 2-4 kids still in the target zone (through age 26), average savings has been significant. About $700/mo to $1,000/mo! But I have to remind them, that it’s not savings; it’s cost shifting. It’s an Advanced Premium Tax Credit (APTC). So the taxpayers are paying it.

In many cases, the APTC is LARGER than the entire premium they paid last year. AND they pay their own additional premium this year too. So the cost is HIGHER, but it’s MASKED by this enormous TAX CREDIT.

The exception:

Single guy on disability: He is able to pick up a $768/mo plan for $305/mo. That seems like quite a savings! But if you look, you will see the $463/mo taxpayer credit.

Some of the Winners don’t even know it yet! 

AND a part of the cost savings for families comes from moving their kids from private insurance to Medicaid (in California it is Medi-Cal). So a guy owns a business, married to stay-at-home mom, vehicles include Super Duty truck, Range Rover, Dodge Viper and more. Other toys (boats) too. And we are moving his kids onto Medi-Cal. Really?!?!

Friday, December 20, 2013

Obama blinks!

Obama blinks!

Another arbitrary move that messes up the market place.

If you don’t want to change to the new Obamacare health plans, you can qualify for a one year exception. MAYBE! Only if you received a cancellation notice from your current carrier.

Today Show video explaining President's new position

Another fix for the botched rollout.

  • One year exemption from penalties
  • Buy catastrophic coverage (previously limited to those under 30)

Deadline is 3 days away if you want uninterrupted coverage.

So the law says you could buy catastrophic coverage (much less expensive) if you’re under 30, but the administration has opened that trick up to everyone who has received a cancellation notice. Of course the reason they’re receiving the cancellation notice is because their current policy doesn’t cover the expanded government wish-list (characterized as the 10 essentials of health insurance coverage).

So the government says you have sub-standard health insurance if it doesn’t cover maternity (even for males and couples past child-bearing years), pediatric dental (even if you don’t have kids) and expanded mental health services (even if you never needed them or wanted them).

Follow the logic...

  1. If you don’ t have these 10 ‘essentials’, you have sub-standard coverage.
  2. Obamacare outlaws sub-standard coverage.
  3. Your insurer is required to cancel your sub-standard policy.
  4. You can now ignore the penalties for a year or get catastrophic coverage which has even fewer benefits than the ‘sub-standard policy’ it is replacing.

BTW, there are more uninsured people in the US today, than when ACA was passed. I thought ACA was supposed to make insurance more affordable and reduce the number of uninsured.
WRONG ON BOTH COUNTS!!!

Of course, insurers are deeply concerned — they are forced to change their tried-and-true business model by doing the following: 

  • Take all comers, even those with massive near-certain health costs
  • Charge way more than they think people want to pay
  • Force their clients into government-run insurance exchanges as the ONLY WAY to get affordable coverage.
  • Offer VERY limited networks of providers on those exchanges (it's the only way left to insurers to try to control expenses).
  • Pay kickbacks to government programs (through exchange fees, government reinsurance fees and more).
  • Watch the system collapse or suffer huge premium increases with government-backed profitability guarantees for only 3-years, and out-of-control premium increases as healthier, younger consumers steer clear of what is being perceived as a trainwreck.

Thursday, December 19, 2013

The Nightmare before Christmas

The Nightmare before Christmas


’Twas two nights before Christmas and all through the house
  not a person was covered, not even a mouse.

  The website was broken and when I would call
  Covered California had hold times that would stall, stall, stall.

  The list of doctors and hospitals was far from complete
  You’d have to look up each one and call them, by Pete.
                 With apologies to Tim Burton and Clement Clarke Moore


Yes. Today hold times at Covered California are 45 minutes to an hour.
If you call the number listed in their ads, you are told to HANG UP and call one of two other numbers — no reason given as to why there are two numbers, or if there are any reasons to call one over the other. BTW, you get the same message (IN ENGLISH!) when you call the SPANISH phone number. And they wonder why Spanish-speaking signups so far are practically ZERO. Geniuses!


The agent phone number isn’t working. 

Which makes sense. If you don’t have answers for the professionals you partner with, just don’t answer the phone.

So I have to call the main line and ask questions from the customers’ perspective.
Today I called in to ask whey I had to drive past 14 hospitals to get to the one 25 miles away (over an hour away in drive-time) as it is the ONLY ONE listed in my Enhanced Silver HealthNet HMO plan. The perky elf on the helpline said not to worry, not all of the hospitals are put in yet. They’re still working on it.


Then she wanted to know where I found a list of hospitals on the plan. “It doesn’t make sense that other hospitals aren’t in the plan. Just CALL each one and ask if they participate in Covered California, with the insurer name.”


I agree. It doesn’t make sense at all. The problem is... do I trust their assurances? Do I tell every client to call every doctor and hospital they want to use. BTW, many doctors offices don't know the details of all of these new plans, either. Just because they accept HealthNet HMO doesn't mean that they accept Enhanced Silver HealthNet HMO through Covered California.


AND Keep in mind this all has to happen BEFORE the deadline of December 23.


Here are some of the broken links. Interesting: NONE of the resources listed (in red) actually work.

Oops! The page you're looking for is no longer here...

Spanish, the missing language!

And, in care you are wondering, here is a list of languages at the Covered California website. Now I would typically expect that ENGLISH and ESPAÑOL would be close to one another, in importance AND alphabetically. But look at where Spanish is listed... 11th on the list. The list is so long, Spanish doesn't even show up on most computer screens without scrolling. Español (Spanish) is after Hmoob (Hmong), Korean and Russian, but before Filipino and Vietnamese. Is the list in alphabetical order? NO! In order of importance (number of California speakers)? NO! It is oddly random.

And they wonder why nobody Spanish-speaking is signing up. 
Geniuses!


Saturday, December 14, 2013

You’re never more than a minute away from another problem

You’re never more than a minute away from another problem

How do you describe your experience on the CoveredCA website — the health exchange for California? Here is an experience with an actual client.

Sure he was incredulous when I showed him that his family would save $7000 a year. Actually that’s a little misleading. The insurance itself costs $2000 MORE than his off-exchange policy. It’s the taxpayer subsidy that brings the cost way down. That and shifting his kids to Medi-Cal (California’s version of the welfare program Medicare).

So the insurance costs more, but since it’s subsidized he pays a lot less. So it’s the taxpayers who are getting soaked! And since the client doesn’t pay the higher costs (yet) he is less likely to worry about them. Genius!

But then there is the issue of actually signing up. I helped him, step by step. Over the course of 2 hours: the website failed and kicked us off no less than 5 times. At one point we called the helpline for Covered California. We enjoyed their upbeat hold music for about an hour before we got through. We had moved past the original problem by then, but were glad we had stayed in the hold queue.

We found the doctors, we found the plan, we did everything and hit the button to choose a plan. Bamm! Kicked out again. About this time the client said the website experience was so frustrating that he would have given up some time ago. He summed up his take on it by saying “You’re never more than one minute away from another problem.”

Recipe for Massive Subsidy on Health Premium

Self-employed, married, 2 or more kids (including young adults in college, after college or performing volunteer service abroad). Of course you don’t have to be married, any household of multiple people will help you secure the subsidy.

• Control over your income (keep it in the $50k to $60k range—see the chart below)

•File your 2014 taxes by April 15, 2015.

Yes, we refer to information from you 2012 taxes to predict taxes on income that hasn’t happened yet, and which won’t even be reported until April 2015. Based on that, you receive a subsidy of $700/mo to $1000/mo. Which helps you not to notice that the unsubsidized premium is higher than you expected.

I have a special chart which shows a couple of important things.


First, where do you qualify for the subsidy. IMPORTANT! If you make too little you get NO SUBSIDY because you should be on Medi-Cal. And you have to make less than 400% of the Federal Poverty Level to qualify for ANY subsidy. So find your houehold size (first column), and see the income for 138% to 400% of FPL. For a larger family, say a couple, 2 kids in college and 2 kids at home, that would be...$10,500 a month.

But if you make less than 250% of FPL, say $78,975 a year, you qualify for Enhanced Silver Benefits. That means much smaller deductible, AND many services with NO DEDUCTIBLE. If you are in the golden square above, you qualify for Enhanced Silver Benefits.

Many business people who qualify for these generous subsidies don’t even know it.

So what could someone do with the savings? 

Pay for Long-Term Care insurance. Give it to your kids. Retire early. Adult orthodontia. Buy more life insurance. Take extra vacation time. Use some of it to go see the doctor you want.

Contact me and I’ll send you some helpful information. It includes the chart above, along with additional information about Obamacare. To know where you stand you need to know:
  • The benefits
  • The cost
  • The penalties for not having it
  • The exceptions

For some people, the penalty for not having insurance may be MORE than the (subsidized) premium. You owe it to yourself to find out where you stand.

And if you are part of a business: small businesses (less than 100 employees) can OPT OUT of many of the most onerous features of Obamacare. I can get you information on that as well. Opting out works best for 10-99 employees, but things can be done even for those with less than 10 employees.