Need to Know: Health Plans & Medical IRAs

Need to Know: Health Plans & Medical IRAs
We are available for personal consultation. No cost, no obligation. Just contact us.
Showing posts with label obamacare. Show all posts

Saturday, July 16, 2016

COBRA bite -vs- Medical IRA

Got a call yesterday from a client. 2 years ago, she dropped ACA coverage when her husband got a job that offered employer-paid health insurance. That’s the way it’s supposed to work. Now he is making a change and they along with their 4 kids have COBRA coverage. With COBRA , they pay 102% of what his employer-paid plan costs: about $2000 a month.

ACA silver coverage would cost them about $1450 a month. With a $950 a month subsidy, that nets out to $400 a month. Not bad!

But the real question: Do you go to the doctor a lot? Any chronic illness (like diabetes)? Many prescriptions? No, no, no.

Have you considered a Health Savings Account (HSA)? 

At one time the husband had a Flexible Spending Account (FSA) through his employer. FSA is “Use it or lose it” with only a small amount that can carry over from year to year.

With HSA, what you don’t use is YOURS TO KEEP. And you can save/invest it just like an IRA.


The key benefit

Money goes Tax-Deductible IN, Tax-Free OUT for medical purposes (even if they aren’t covered by your major medical plan). At retirement age, the money can be used for any purpose just like an IRA.

HSA is a Medical IRA. It is SUPERIOR to the typical IRA. Why? Typical IRAs only provide a one-sided tax benefit. Either they are Tax-Deductible IN (traditional IRA for those who qualify) or Tax-Free OUT (Roth IRA, but only when the account has been established at least 5 years AND the client is over 59 1/2).

HSA has 3 tax advantages...

     1) Tax-Deductible IN (regardless of income levels that would disqualify typical IRAs) and
     2) Tax-Free OUT (immediately, no 5 year wait like Roth IRAs) and
     3) Qualified medical expense acts as a Get-out-of-jail-free-card for your money. (Now or later)

For item 3: You can use it right away, or use it to make a tax-free withdrawal years into the future. AND recognized medical use includes things like premiums for Long Term Care insurance, mileage expense and lodging for medical, orthodontia, vision, etc.

But to get these benefits, you need a High-Deductible Health Plan (HDHP). Conveniently, these usually have HSA somewhere in their name. Unfortunately, Covered California usually only has 1 or 2 HDHP choices in its lineup.

The cost?

In this case, the bronze 60 HSA-compatible plan costs $4.30 per month... for the whole family.
They can take a PORTION of their COBRA premium and stash it into their HSA. With their HSA, they can see any doctor. (One of the big bugaboos for ACA has been the restricted doctor networks.) If a doctor’s visit costs $100 or so (cash discount available for the asking), they come out ahead even if their usage is 20x what it has ever been. They will save up the whole ANNUAL deductible for their bronze plan in a matter of months.

Typical story. High cost COBRA: $2000/mo. Lower cost individual plan: $1450/mo. Net ACA cost: $400/mo. or $4.30/mo and SAVE THE DIFFERENCE.

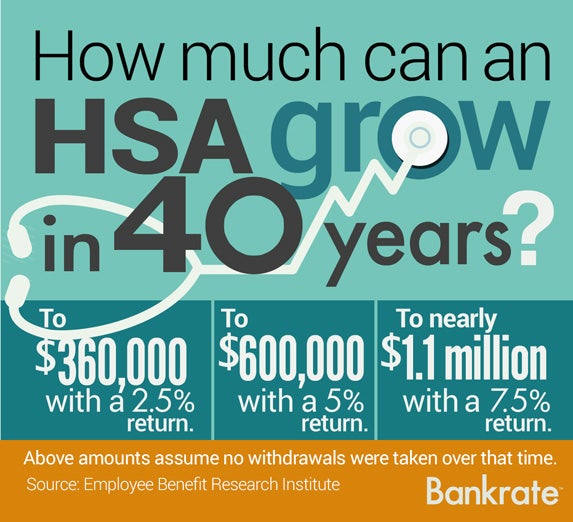
BTW, I have clients who have used HSA for over 10 years. Some have balance of $50,000 or more. What is the long-term potential?

Wednesday, April 22, 2015

It's over in 8 days. We mean it this time!

The bureaucrats have changed their minds before. These are the last 8 days to buy health insurance for all those who 'didn't know' they would have to pay a penalty if they didn't have coverage. Smart, eh? Let the tax preparer tell you to go out and buy health insurance.

To answer the above question: Don't hold your breath.

The geniuses at Obamacare think they'll get more people covered by making it illegal to sell health insurance 305 days out of the year. 

Artificial scarcity. Usually, there are only 60 days in a year when people can buy individual/family health insurance. That is the 'open enrollment' period which runs from mid-October to mid-December. Unless political consequences get in the way and they move it (to avoid an issue with election fallout) or extend it (like they did the first year). Or re-open it as they did this year through April 30, 2015.

And there are about a dozen circumstances which allow for a 'special enrollment period' at other times of the year including my favorite: because we (the bureaucrats at the healthcare exchange) feel like it.

What happens if you don't buy health insurance?

For 2014, the penalty was $95 per person or 1% of yearly income per person (for the whole family) --whichever is larger.
In 2015, the fee increases to $395 per person or 2% of yearly income per person (for the whole family) --whichever is larger.
In 2016, the fee increases to $695 per person or 2.5% of yearly income per person (for the whole family) --whichever is larger.
The penalty is capped at the average yearly premium for a Bronze plan (the cheap plan), which is insurance that pays an average 60% of the cost of health care.
Children count half (each) and families are capped at 3x the above per-person numbers. So if it's a single parent with more than 4 kids... they're in luck!

So if you have a family with mom and dad and 3 kids... that's 2 x 2% (adults) + 3 x 1% (children) = 7%. That's 7% of their income. That's a huge chunk of money for a whole lot of nothing. Remember, that doesn't pay for coverage or anything else for them. It helps subsidize all those who get coverage for free or at greatly reduced cost.

Friday, December 20, 2013

Obama blinks!

Obama blinks!

Another arbitrary move that messes up the market place.

If you don’t want to change to the new Obamacare health plans, you can qualify for a one year exception. MAYBE! Only if you received a cancellation notice from your current carrier.

Today Show video explaining President's new position

Another fix for the botched rollout.

  • One year exemption from penalties
  • Buy catastrophic coverage (previously limited to those under 30)

Deadline is 3 days away if you want uninterrupted coverage.

So the law says you could buy catastrophic coverage (much less expensive) if you’re under 30, but the administration has opened that trick up to everyone who has received a cancellation notice. Of course the reason they’re receiving the cancellation notice is because their current policy doesn’t cover the expanded government wish-list (characterized as the 10 essentials of health insurance coverage).

So the government says you have sub-standard health insurance if it doesn’t cover maternity (even for males and couples past child-bearing years), pediatric dental (even if you don’t have kids) and expanded mental health services (even if you never needed them or wanted them).

Follow the logic...

  1. If you don’ t have these 10 ‘essentials’, you have sub-standard coverage.
  2. Obamacare outlaws sub-standard coverage.
  3. Your insurer is required to cancel your sub-standard policy.
  4. You can now ignore the penalties for a year or get catastrophic coverage which has even fewer benefits than the ‘sub-standard policy’ it is replacing.

BTW, there are more uninsured people in the US today, than when ACA was passed. I thought ACA was supposed to make insurance more affordable and reduce the number of uninsured.
WRONG ON BOTH COUNTS!!!

Of course, insurers are deeply concerned — they are forced to change their tried-and-true business model by doing the following: 

  • Take all comers, even those with massive near-certain health costs
  • Charge way more than they think people want to pay
  • Force their clients into government-run insurance exchanges as the ONLY WAY to get affordable coverage.
  • Offer VERY limited networks of providers on those exchanges (it's the only way left to insurers to try to control expenses).
  • Pay kickbacks to government programs (through exchange fees, government reinsurance fees and more).
  • Watch the system collapse or suffer huge premium increases with government-backed profitability guarantees for only 3-years, and out-of-control premium increases as healthier, younger consumers steer clear of what is being perceived as a trainwreck.

Wednesday, December 4, 2013

Do as I say, not as I do...

White House: No Updates On When Obama Will Sign Up For ObamaCare (Dec 2, 2013)


Carney: Um, No, Obama Hasn't Signed Up For ObamaCare Yet, But Hey, He's Going To, Really 

White House Press Secretary Jay Carney admitted to reporters Monday that Barack Obama has not yet enrolled in ObamaCare, saying “I know he will and has said that he will…but I don’t have an update.”

When asked what Obama was waiting for and whether the White House would announce it when he does sign up, Carney laughed uncomfortably and said: I’ll get back to you on that.”

Sunday, December 1, 2013

Self-imposed (but vague) deadline for website fix


November 30th has come and gone. Will the website experience be improved? The improvement goals were really vague: A better experience for the ‘majority’ of users, while the ability to pay for the plans hasn’t been finished.

And there is still the issue of ‘orphan plans’: people who thought they signed up, the website told them they signed up, but the website didn’t actually transmit the data to the insurance company. Meaning, they have no coverage; but won’t find out about it until they try to use the non-existent medical coverage, presumably, for something important.

Of course, the government considers the website improvements to be a success if 80% of the people can create an account. Oh dear, nothing there about actually procuring and paying for a policy. Estimates are that 10% of people will still get dropped from the system.

And the administration is in a tough spot. They encouraged people to have the ‘turkey talk’ with their families about getting health care. But they can’t encourage everyone to go to the website, because that would definitely overload the system. Instead, they encouraging their supporters to use the website at off-peak hours and weekends.

The real question is: is it a good thing that the website works better?

So far Medicare enrollment has increased by 35%. That is a lot more people getting health care, but no one putting more money into the system.

Young adults (through age 26) can stay on their parents policies. That used to be free, but now is a cost item -- so what's the advantage? And now I have to collect W2s from the adult-kids of my clients before I can tell the parents how much their health insurance will cost.

The ACA amounts to a de-facto tax of 9% on the self-employed. That's on top of other self employment taxes that currently amount to 15.3% and before the new ACA surcharge of 0.9% (on earnings more than $200k). That's a total of 24.3% to 25.2%, BEFORE federal and state income taxes kick in.
CBS News: when to pay self employment tax

How many start-ups and entrepreneurs will end their year earlier (aka stop earning money) when they approach certain limits rather than pay higher taxes and surcharges. Small business owners usually have cars, computers, internet and other things paid for by the business. So they end up with a lot of flexiblity over how much they earn and when, without disrupting their lifestyle.


That also leads to millionaires (with low MAGI) qualifying for MAXIMUM TAXPAYER SUPPORT on their health insurance.

And about the only cost-containment tool the insurers and hospitals can use is to limit which hospitals and doctors you can actually use. You go to the hospital only to find out “you choose poorly” (apologies to Indiana Jones and the Last Crusade).

Thursday, November 28, 2013

SHOP: Latest Obamacare website delay.

It hasn’t been a good couple of months for the Obamacare tech team. The website and its developers have drawn strong criticism for abysmal performance. A promise to fix it by the end of November now has Secretary Sibelius saying “There’s nothing magical about the December 1 date” (paraphrase).

They moved back the open enrollment deadline for NEXT YEAR in an obvious attempt to get EVEN HIGHER RATE INCREASES and voter wrath delayed until after the mid-term elections.


And now, this. SHOP (the small business health insurance tool) will not have web functionality until November 2014. A whole year delay. That’s interesting because unlike consumers, who can only buy insurance during open enrollment periods, businesses can buy insurance ANY TIME THEY WANT.
Politico: SHOP enrollment delayed by one year
Huffington Post: Small business exchange delayed a year

So, why a whole year delay? Good news, we’re back online in September? See, we beat our self-imposed deadline by a month! OR are they afraid the “real” date won’t be until 2015?

Either way, businesses aren’t chomping at the bit to ADD huge new expenses in a prolonged downturn with still-too-high unemployment and economic uncertainty--thanks to... wait for it... Obamacare.

The administration celebrates as tens of thousands sign up, while forcing millions to loose coverage, in spite of direct and repeated assurances of the opposite. Could it be that, so far, Obamacare has caused far more problems than it has solved?

Your best bet is STILL to use a broker!! Same thing as before the magical rollout of Obamacare. A broker can help you compare Obamacare rates and apply this year using, get this, a paper application! A broker can also help compare non-Obamacare rates, something the website CAN’T do and WON’T do, even next year. Why limit your choices?

If you use the right broker, your small business can choose from programs that offer:

    > Tax-advantaged medical IRAs
        Health Savings Accounts for employees
        Health Reimbursement Account for employers
        Available to any size employer

    > Partial self-funding
        Potentially HUGE refunds of excess premiums
        The only way to recoup smoker-penalty rates (in states like California)

These tools were quite helpful in recent times. They are now even more important in that they allow you to have more options and reduced cost.

Thursday, November 21, 2013

CoveredCA to Pres. Obama: "Drop Dead"

Covered California (the state’s health exchange) to President Obama: “Drop Dead”

 
California rejects President Obama’s plea to allow consumers to KEEP their health plans, as he promised repeatedly in the months leading up to passage of ACA. Last week, the President apologized for the botched rollout and said that he would magically extend the deadline for individuals to switch from the insurance policies they like (and want to keep) to the overpriced ones he thinks are better for them.

“That means that no matter how we reform health care, we will keep this promise to the American people: If you like your doctor, you will be able to keep your doctor, period. If you like your health-care plan, you’ll be able to keep your health-care plan, period. No one will take it away, no matter what.”
– President Obama                                     Speech to the American Medical Association
                                    June 15, 2009 (as the health-care law was being written.)


That’s a big deal because the President’s credibility is on the line. Mitt Romney said the original Obama promise showed ‘fundamental dishonesty’.  Interesting note: Bing search for ‘fundamental dishonesty’ shows 17 out of 18 top hits relate to Romney’s quote and Obamacare. Former president Bill Clinton told Obama that he needed to make good on his promise. So the President, without force of law or congressional approval, unilaterally decided to extend the deadline for a year. Not even close to the ‘keep it’ promise, but it was a step in the right direction.

Unfortunately, extending the deadline can ruin participation in the MUCH MORE EXPENSIVE Obamacare health plans. So Covered California rejected the delay. That’s important because any insurance company that is listed on the CoveredCA exchange (BTW, they pay a lot of money for the right to be on the exchange) signed an agreement that they would DISCONTINUE their non-ACA compliant (read AFFORDABLE) health plans. That means that CoveredCA (not the President, not the governor, not the insurance commissioner) decides when these plans will be discontinued. And it wants them discontinued without delay.


So now, beleaguered Californians are faced with new ACA-compliant policies. And premiums that are 64% to 146% higher, for starters. Check out this excellent Forbes article. Lack of participation by overcharged youth (who often go YEARS without needing a doctor even once, much less enough to justify even ONE MONTH’S ACA PREMIUM) could cause premiums to SKYROCKET further in coming years. And as a special bonus, Obamacare promises to pay insurers TAXPAYER SUPPORTED PROFITS for the first 3 years, on top of potentially skyrocketing premiums.

California boots non-Obamacare plans  รง Another article that tells it like it is.
“The move effectively rejects the fix President Barack Obama proposed to salve the deeply troubled rollout of the Affordable Care Act. That state already faces an age-old health insurance challenge: The old folks are outrunning the kids in the race to sign up for California’s insurance. If the trend continues, it might [might????] lead to higher premiums down the line.”

‘Fundamental Dishonesty’

Wednesday, November 20, 2013

Oregon health care exchange website NEVER worked, has NO subscribers

Oregon health care exchange website never worked, has no subscribers

Wow, that headline writes itself. BTW, here is the link to the story at NBC News:
nbcnews.com/health/oregon-health-care-exchange-website-never-worked-has-no-subscribers

Here's the website: CoverOregon.com

Funny how the website NEVER MENTIONS that it doesn't work, and is actually WASTING YOUR TIME.


National Roll-out

Reports are coming in that out of the 500,000 people who looked at a plan (nationally), 106,000 'selected a plan'. Notice the odd phrasing, there; it doesn't mean they actually bought a plan or paid for it. Only about 27,000 people 'bought' plan. Most of those are older, sicker--not the needed demographic of young, healthy people (YHP).

And why should they attract YHP. Obamacare artificially RAISES the premium on this group. So we have a group we desperately need to enroll to make the whole thing work, so we CHARGE them MORE. By the way, it's not a little more, it's a lot more.

This is the healthy group which may go YEARS without spending a DIME on urgent medical care. Studies have shown that even in FULLY INSURED groups of employees, upwards of 6 out of 10 won't go to a doctor in any given year.

Another note of interest

In California, the ratio is 4:1 of people who are signing up for Medi-Cal (free) compared to those who are signing up for Obamacare (actually pay for it). Of course, those that pay find out Obamacare is way more than you expected, unless you factor in a taxpayer subsidy. These subsidies are so pervasive, that a family of four can qualify for premium subsidies with up to $95,000 of household income.

Is it a good thing to tell moderately high earners that the government has to subsidize their purchase? And this taxpayer subsidy is ONLY AVAILABLE through the federal and state exchanges. If you have been using a privately purchased individual plan, YOU DON'T QUALIFY for a dime of that subsidy--you have to change to an exchange-based health plan (even if it's with the same provider).

Thursday, November 14, 2013

Obamacare Band-Aid? Keep your plan (until Dec 31, 2014)

US President Barack Obama speaks
“If you like your plan, you can keep your plan. Period.” *
              *until Dec 31, 2013 — oops, make that Dec 31, 2014. President Obama.
 
A one-year extension?
At his press conference announcing this one-year extension, Pres. Obama talked about insurers possibly charging 20% more than they did last year, for ‘lesser’ coverage. Of course the ACA-compliant health care premiums (for many) are 50% higher than last year. And it includes things like maternity care for people not of child-bearing years (or gender for that matter). It includes pediatric dental, rehabilitative services and mental health coverage. It also includes charging the YOUNG extra to offset the true premiums for the ELDERLY. Given a choice, many people DON’T WANT and DON’T NEED and CAN'T AFFORD these coverages.
People just aren’t smart enough to know what they want, what they need, and what they can afford. So government better tell you, and then force you to buy it. And if you don’t buy it, we’ll get the IRS involved.

But wait, there’s more!

The other issue, asleep, but ever-present: ANY delays in full implementation of ACA run the risk of people putting off (or refusing) enrollment in the new programs. That means that only the sick and highly subsidized will sign up. That combo really throws off the cost curve. Since insurers set rates for 2015 based on their  costs (loss experience) in the first part of 2014 (among other factors), premiums for 2015 could go up dramatically.
NBCnews says: One fear is that if too many people are allowed to keep their older, cheap policies, they won’t join the pool of people buying on the exchanges – and that’ll drive up prices next year for everyone else. The more healthy people are in the pool buying policies, the more they offset the sicker people in the pool, and the less insurance companies can charge everyone...
Price is the main concern of most Americans when it comes to buying insurance, and the Obama administration is keen to be able to say Obamacare is keeping prices low.
Good luck with that. Out of 10 Essential Coverage items, most people don’t want (or need or want to pay extra for) at least 3 or 4 of them. Those ‘extra’s which the government deems essential DRIVE UP THE COST. Covering sicker people (uninsurable, in underwritten policies) for the same price as the healthy, DRIVES UP THE COST. Extending coverage to illegal aliens while specifically exempting them from paying into the system, DRIVES UP THE COST. Paying millions to leftist groups for ‘marketing’ and awareness campaigns, DRIVES UP THE COST.
When private insurers do marketing-type things, they have to be accountable for the cost and benefit of these decisions. When government does it, it becomes yet another  slush fund.

Wednesday, November 13, 2013

New Obamacare Ads Are Out!

Remember: you are paying for this. Not just the birth control, but the ads, too. Now that Ali and Suzie Hot-to-Trot have free birth control, they need to maximize their opportunities. “All I have to worry about is getting him between the covers.”

Oh and the all-important fine print says that condoms and common sense can protect her from STDs. Do these ads offer any semblance of common sense? Check out the one for ‘brosurance’ with  the guys doing a keg stand. Way to promote common sense!

Here's the post from chicksontheright.

Like, OMG! New Obamacare Ads Are Out!

As if keg stand ads weren't enough to make you look at this administration and know that we're surely doomed. Now Obamacare is pushing these totally awesome ads, which happen to reside on the aptly named "DoYouGotInsurance.com" website, because why on earth would we use correct grammar when speaking to complete low-level-voting Democrats, right?  (Oh, and PS - I tried clicking it a few times this morning and the link wasn't working when I did.  SHOCKER.)
Anywho, here are some of the gems you can see in the new campaign, obviously created by folks who were fired from MTV and Miley Cyrus' last twerking tour, soon to be hired as some sort of Czars on Obama's staff.  Naturally.


Isn't that neat, you vapid skanks?  YAY!
And let's not forget this one, which is also a lot of fun (Wheeeeeeeeeeeeeeeeee!!!!!!!!!!!!!!!!):

They so CRAZY, those Obamacare folks.
Stay classy, Amerika.