Need to Know: Health Plans & Medical IRAs

Need to Know: Health Plans & Medical IRAs
We are available for personal consultation. No cost, no obligation. Just contact us.
Showing posts with label medical IRA. Show all posts

Saturday, July 16, 2016

COBRA bite -vs- Medical IRA

Got a call yesterday from a client. 2 years ago, she dropped ACA coverage when her husband got a job that offered employer-paid health insurance. That’s the way it’s supposed to work. Now he is making a change and they along with their 4 kids have COBRA coverage. With COBRA , they pay 102% of what his employer-paid plan costs: about $2000 a month.

ACA silver coverage would cost them about $1450 a month. With a $950 a month subsidy, that nets out to $400 a month. Not bad!

But the real question: Do you go to the doctor a lot? Any chronic illness (like diabetes)? Many prescriptions? No, no, no.

Have you considered a Health Savings Account (HSA)? 

At one time the husband had a Flexible Spending Account (FSA) through his employer. FSA is “Use it or lose it” with only a small amount that can carry over from year to year.

With HSA, what you don’t use is YOURS TO KEEP. And you can save/invest it just like an IRA.


The key benefit

Money goes Tax-Deductible IN, Tax-Free OUT for medical purposes (even if they aren’t covered by your major medical plan). At retirement age, the money can be used for any purpose just like an IRA.

HSA is a Medical IRA. It is SUPERIOR to the typical IRA. Why? Typical IRAs only provide a one-sided tax benefit. Either they are Tax-Deductible IN (traditional IRA for those who qualify) or Tax-Free OUT (Roth IRA, but only when the account has been established at least 5 years AND the client is over 59 1/2).

HSA has 3 tax advantages...

     1) Tax-Deductible IN (regardless of income levels that would disqualify typical IRAs) and
     2) Tax-Free OUT (immediately, no 5 year wait like Roth IRAs) and
     3) Qualified medical expense acts as a Get-out-of-jail-free-card for your money. (Now or later)

For item 3: You can use it right away, or use it to make a tax-free withdrawal years into the future. AND recognized medical use includes things like premiums for Long Term Care insurance, mileage expense and lodging for medical, orthodontia, vision, etc.

But to get these benefits, you need a High-Deductible Health Plan (HDHP). Conveniently, these usually have HSA somewhere in their name. Unfortunately, Covered California usually only has 1 or 2 HDHP choices in its lineup.

The cost?

In this case, the bronze 60 HSA-compatible plan costs $4.30 per month... for the whole family.
They can take a PORTION of their COBRA premium and stash it into their HSA. With their HSA, they can see any doctor. (One of the big bugaboos for ACA has been the restricted doctor networks.) If a doctor’s visit costs $100 or so (cash discount available for the asking), they come out ahead even if their usage is 20x what it has ever been. They will save up the whole ANNUAL deductible for their bronze plan in a matter of months.

Typical story. High cost COBRA: $2000/mo. Lower cost individual plan: $1450/mo. Net ACA cost: $400/mo. or $4.30/mo and SAVE THE DIFFERENCE.

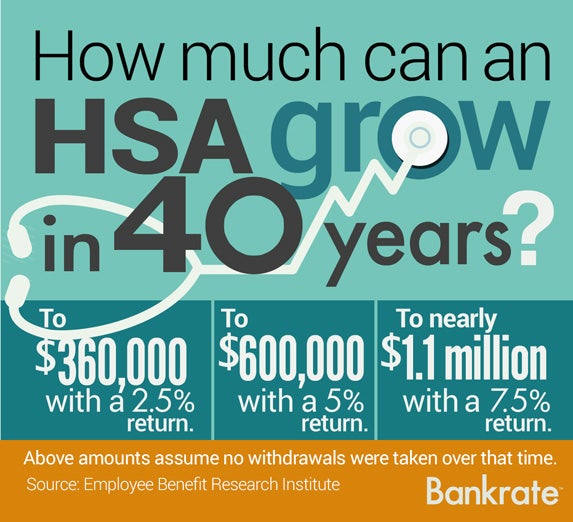
BTW, I have clients who have used HSA for over 10 years. Some have balance of $50,000 or more. What is the long-term potential?

Thursday, November 21, 2013

Business Health Plans

Obamacare not only impacts the individual market for insurance, it also impacts businesses as well. New regulations, fees, taxes and penalties are always unwelcome. They stifle job creation and are especially problematic for self-employed, start-ups and small business. But the new Obamacare regime also limits the choices offered through these plans.

When a business offers health care, it has to offer everyone the same metal tier. The metal tiers (bronze, silver, gold, platinum) sound the same as those in the individual marketplace; but they are, in fact, different.

Not only that, but once a business picks a tier — say GOLD — now ALL employees have to select from that tier. Individuals can't pick a PLATINUM plan for higher benefits or a BRONZE plan because they don't use much in medical services and are in good health.

So if you have people who make a lot of money (the owner, key executives) you would want a higher metal tier. But that means the hourly workers don't have access to an "affordable" plan--which means they can go to the exchanges. It also means the employer is subject to a fee/penalty/tax for not offering an affordable plan.

If the employer offers a low-cost bronze plan, the higher-income employees are STUCK with a plan that pays a LOW ACTUARIAL VALUE.

What they don't tell you, is that there is a way for businesses large and small to OPT OUT of this. You won't find out about this option by doing any of the following...


The only way to find out about this options is to work with an insurance agent that is authorized to offer it. The good news, working with an agent doesn't cost more money (even on the government exchanges), and it could save you tens of thousands. You could possibly save much more.

You don't have to settle for a bad insurance plan designed by the government. Those plans include mandated extras like maternity care for men, pediatric dental, no non-smoker discount, and more. That may be acceptable to the ruling elite, but most people don't like paying for things they don't want. And many of your employees won't like paying for things they don't actually use.

Did you know that upwards of 6 out of 10 employees (in almost any size group) never even use their medical insurance? Not even once in a 12 month period! Does it make sense to get a refund on premiums for care that wasn't actually used? Does it make sense to recapture the smoker rates and poor-health rates built into every premium dollar under Obamacare?

Contact us and we will get you information on how to OPT OUT. Potentially qualify for lower premiums. Experience total value and total control by putting money into a medical IRA. Businesses with 10 or more employees may even qualify for a substantial return of premium dollars. 

Find out what you don't know. You'll be glad you did.